How a Bank Can Launch a Card-Linked Offers Programme in 30 Days
Launching an offers programme does not have to be a year-long IT project. Here is a practical, week-by-week plan for going live in a month.
Many banks assume a card-linked offers programme means a long procurement cycle, a heavy core-banking integration and a year of delivery. It does not have to. With the right platform and a focused team, a bank can move from decision to live cardholder offers in about 30 days.
This guide sets out a realistic four-week plan. It assumes you are using a ready-made platform rather than building from scratch, and that you start with a focused scope you can expand later.
Before day one: agree what "launch" means
The fastest launches are the ones with the clearest definition of done. Before the clock starts, agree on:
- Which cards are in scope. Many banks start with one or two products, for example a Platinum credit card and a flagship debit card.
- Which channels. A white-label offers website and app can go live quickly; embedding offers inside the existing mobile banking app can follow in phase two.
- Which cities or categories. Launching with a dense cluster, such as dining and wellness in the capital, beats a thin spread across the whole country.
- Who owns it. Name one product owner with authority to make decisions quickly, plus contacts in compliance, IT security, marketing and merchant acquiring.
Week 1: set up the foundations
Configure the programme
Set up your bank's space on the platform: branding, colours, logo, languages (for GCC markets, Arabic and English from the start), currency, and the card products you want to support. Define the card ranges (BINs) that are eligible.
Choose the integration path
There are usually three options, and you do not need the most complex one to launch:
- File-based. Exchange eligible card and customer data via secure CSV or SFTP. Simple, familiar to bank IT teams and quick to approve.
- API. Real-time eligibility checks and events. Better for scale, but more testing.
- SDK. Embed the offers experience inside your own mobile app.
Many banks launch on file-based integration and add API or SDK later.
Start the security review early
Share the platform's security documentation with your information security team in week one, not week three. A design that never handles full card numbers, for example identifying cards by first and last digits plus a mobile one-time password, removes most of the PCI DSS questions before they are asked.
Week 2: build the merchant line-up
A programme is only as good as its offers. In week two, focus on getting a strong first set live.
- Start from a shared network. If your platform already has merchants who are willing to extend offers to new banks, you can launch with dozens of offers on day one.
- Add your own relationships. Invite merchants your bank already knows, such as acquiring clients and SME customers. They are often the quickest to say yes.
- Aim for density over volume. Twenty great offers in the neighbourhoods your cardholders frequent beat two hundred scattered ones.
- Use e-signed agreements. Digital merchant contracts with OTP signing turn weeks of paper chasing into minutes.
Make sure each merchant knows how redemption works. A short onboarding call and a printed QR or PIN tent card at the counter go a long way.
Week 3: test with real people
Internal pilot
Invite a group of staff cardholders to use the programme for real. Ask them to redeem offers at participating merchants and report anything confusing. You will learn more in three days of staff testing than in three weeks of document review.
Check the full loop
For each offer type, confirm the complete journey works:
- The customer can find and understand the offer in both languages.
- The merchant can validate it easily, whether by entering the customer's rotating code, scanning a QR code or using a coupon code or tracked link online.
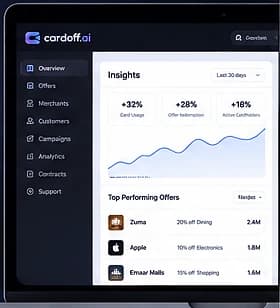
- The redemption appears in reporting for both the bank and the merchant.
- Support questions reach the right team through live chat or tickets.
Tune targeting
Even with a small group, you can check whether offer ranking makes sense. Does a cardholder who mostly spends on dining see dining offers first? Adjust category weights and business rules before launch.
Week 4: launch and learn
Soft launch
Open the programme to a segment of cardholders first, perhaps premium customers or a single city. Watch sign-up, offer views and redemptions daily.
Communicate clearly
Tell customers what the programme is and how to use it. Keep it short:
- A push notification or SMS with a direct link.
- An email that shows three or four standout offers, not a catalogue.
- A banner in internet banking.
- Branch and call centre scripts, so staff can answer questions confidently.
Review after seven days
Hold a short review at the end of the first week live. Which offers are working? Which merchants need help? Are customers getting stuck anywhere? Make changes quickly, then widen the rollout.
Common pitfalls to avoid
- Too many offers, too little relevance. A long list feels like spam.
- Leaving merchants alone. Merchants who do not understand redemption will quietly stop honouring offers.
- Ignoring Arabic quality. Machine-translated copy undermines trust. Write Arabic properly from the start.
- No owner after launch. Offers need weekly attention: refreshing merchants, rotating seasonal deals and reviewing performance.
After day 30
Launch is the start, not the finish. Over the following quarter, most banks expand to more card products, deepen integration via API or SDK, bring offers into the main banking app and grow the merchant network city by city.
cardoff.ai was designed to make this 30-day path realistic: a shared merchant network, file, API and SDK integration options, e-signed merchant contracts and a white-label app and website ready for your brand. If you would like to map out your own launch plan, we would be glad to walk through it with you.